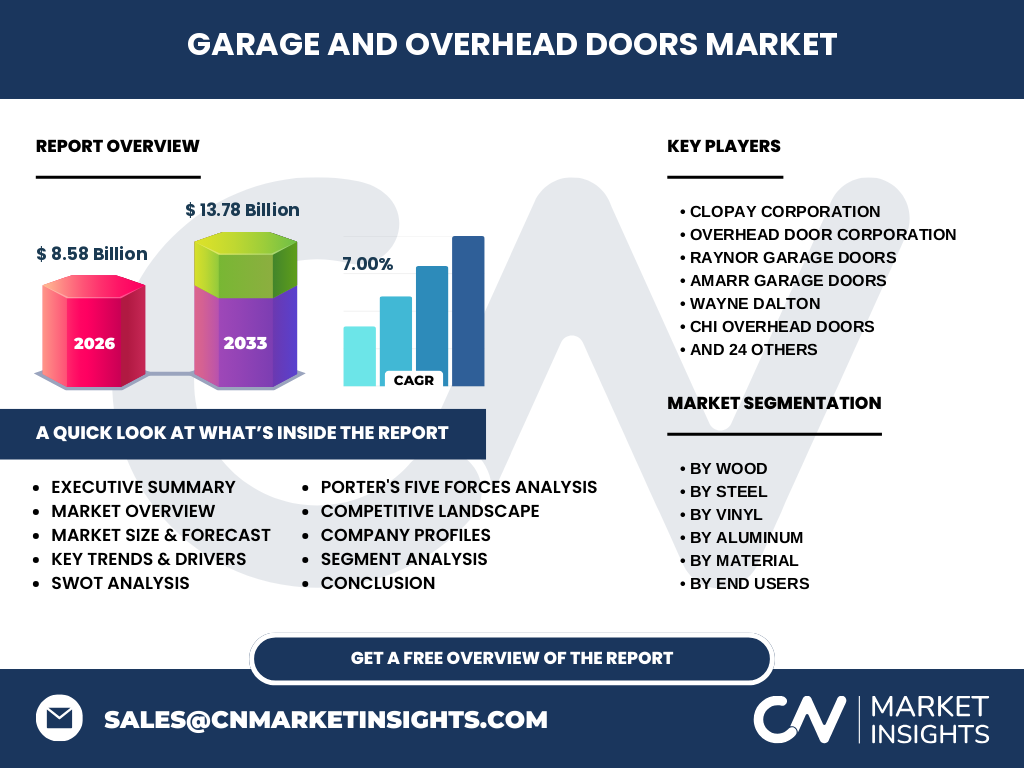
Market overview of the Garage And Overhead Doors Market
Our research indicates the Garage And Overhead Doors Market reaches a valuation of 8.58 Billion in 2026. This sector encompasses engineered entry systems utilized across residential and commercial properties, relying heavily on raw materials like cold-rolled steel, extruded aluminum, and lumber to ensure structural wind-load compliance and thermal efficiency.
Structural Growth Drivers and Market Constraints
The market is driven by surging residential remodeling expenditures and commercial logistics warehousing expansions. However, volatile procurement costs for polyurethane insulation and galvanized steel coils act as prominent restraints. Strict regulatory wind-load mandates from entities like Miami-Dade County dictate severe technical design constraints for manufacturers.
Emerging Industry Trends and Modernization
A definitive shift toward smart-home integration defines current industry trends. Consumers increasingly demand Wi-Fi enabled openers and architectural full-view glass configurations. Companies specializing in corrosion-resistant steel and insulated aluminum are capturing higher margins as property owners prioritize longevity and energy conservation.
COVID-19 Pandemic Impact and Industry Resilience
Supply chain bottlenecks for raw steel and electronic microchips initially crippled production schedules. However, the subsequent home-improvement boom fueled unprecedented demand for residential garage upgrades. The recovery trajectory highlights robust supply chain diversification and localized sourcing strategies among leading fabricators.
Competitive Benchmarking and Market Concentration
The landscape features high market concentration among established titans like Clopay Corporation, Overhead Door Corporation, and Hörmann Group. These dominant entities leverage vast distribution networks and proprietary thermal-break technologies to outpace regional players, intensifying competitive rivalry across standard and custom product tiers.
Executive Summary of the Garage And Overhead Doors Market
Our analysis reveals strong foundational health, projecting the market to surge from 8.58 Billion in 2026 to 13.78 Billion by 2033 at a 7.00% CAGR. Urbanization, architectural innovation, and stringent safety regulations serve as the primary catalysts for this robust valuation expansion.
Long-Term Market Forecast 2027 to 2033
Driven by compounding industrialization and smart infrastructure investments, the Garage And Overhead Doors Market is forecast to achieve 13.78 Billion by 2033. This trajectory represents a steady 7.00% CAGR from the 2026 baseline of 8.58 Billion, favoring automated and thermally optimized solutions.
Comprehensive Segmentation Analysis
The market is segmented by material (Aluminum, Steel, Wood, Fiberglass, Vinyl), end-users (Residential, Commercial), and application (Exterior, Interior). Steel and wood variants dominate residential garages, whereas aluminum and specialized glass systems serve heavy-duty commercial bays and architectural storefronts.
Geographic Distribution and Regional Performance
North America leads global consumption due to aggressive suburban housing construction and rigorous hurricane-mitigation building codes. Meanwhile, Asia-Pacific represents the fastest-growing regional market, propelled by rapid urbanization, expanding logistics hubs, and rising disposable incomes in developing economies.
In-Depth Regional Review and Logistics
North American manufacturing relies heavily on distribution nodes near major freight hubs, while European markets prioritize rigorous acoustic and thermal insulation standards enforced by EU directives. Regional compliance dictates product formulations, especially concerning wind-load resistance and fire-safety ratings.
Strategic Positioning of Leading Companies
Industry leaders such as Amarr Garage Doors, Wayne Dalton, and Raynor Garage Doors differentiate through advanced torsion-spring engineering and expansive dealer networks. Concurrently, specialized innovators like Rytec Corporation and ASSA ABLOY Entrance Systems focus on high-speed industrial rolling doors for cold-chain logistics.
Porter's Five Forces Assessment
Bargaining power of raw material suppliers remains moderate-to-high, directly influencing steel and aluminum pricing. Threat of substitutes is low due to structural safety requirements, while competitive rivalry is intense, compelling established brands to invest heavily in patented thermal-break innovations and smart automation.
SWOT Analysis of the Industry
Core strengths include advanced manufacturing automation and widespread distribution channels. Weaknesses involve high sensitivity to raw material price fluctuations. Opportunities lie in IoT-enabled access control, while threats stem from strict regulatory compliance hurdles and potential macroeconomic downturns impacting construction.
Value Chain Analysis from Raw Material to End-User
The value chain originates with raw metal mining and timber harvesting, progressing through coil coating, insulation injection, and automated fabrication. Finished products flow through specialized wholesale distributors and certified local dealers before reaching residential homeowners and commercial contractors.
Investment Insights and High-Potential Areas
Investors should target manufacturers specializing in impact-resistant vinyl, insulated fiberglass, and integrated smart-home automation. Companies with diversified regional supply chains and compliance capabilities for strict building codes present the most resilient growth opportunities.
Conclusion and Strategic Takeaways
The Garage And Overhead Doors Market presents compelling growth dynamics, underpinned by a forecasted expansion to 13.78 Billion by 2033. Firms that successfully integrate smart technology, sustainable materials, and robust distribution networks will capture outsized market share.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining international trade registry data, primary executive interviews with C-suite stakeholders, and secondary macroeconomic indicators from global construction indices. This multi-layered approach ensures precise market sizing and trend validation.
Scope of the Report and Coverage Parameters
This report covers global market sizing, material-based segmentation, and regional performance metrics from 2026 to 2033. Limitations include inherent forecasting uncertainties tied to macroeconomic policy shifts, global trade tariff adjustments, and unexpected supply chain disruptions.
Recent Industry Developments and Strategic Moves
Recent market activities feature major fabricators launching eco-friendly, ultra-insulated door lines to comply with strict energy conservation codes. Strategic mergers and acquisitions among automated opener manufacturers and traditional door builders continue to consolidate market share and expand product ecosystems.